Best Vacation Rental Access Control Software
Comparent ·
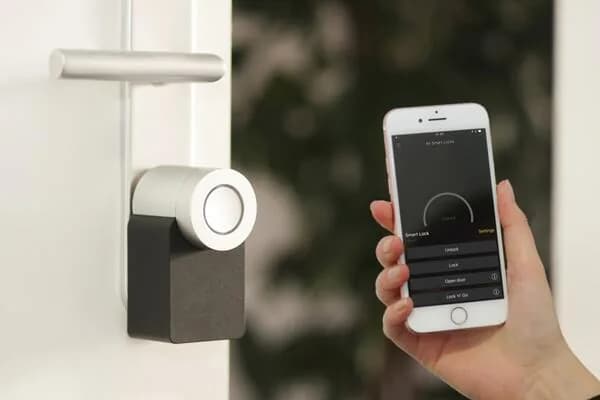
Managing guest access to vacation rental properties has evolved beyond traditional key exchanges, but adoption of smart access control technology remains limited among vacation rental operators. Based on the 2025 Comparent Ultimate Tech Stack Survey of 624 vacation rental companies, only 99 companies (17.0%) use smart home and access control solutions.
Smart home and access control technology, while growing, serves primarily early adopters rather than mainstream vacation rental operations. The survey reveals that 83.0% of operators still manage guest access through traditional methods or basic solutions without specialized smart home integration.
Among the few adopters, Point Central leads with 23 users (23.2% of smart home users), followed closely by RemoteLock with 21 users (21.2%) and Lynx Automation with 18 users (18.2%). This relatively even distribution suggests the market lacks a dominant solution, indicating early-stage technology adoption.
Understanding the current adoption patterns helps operators evaluate whether smart access control provides sufficient value to justify investment over traditional guest access methods.
Key Takeaways
- Only 17.0% of vacation rental operators use smart home and access control technology
- Market leaders include Point Central (23.2%), RemoteLock (21.2%), and Lynx Automation (18.2%) with relatively small user bases
- The 83.0% non-adoption rate indicates most operators manage guest access through traditional methods
- Early adoption opportunities exist for competitive differentiation, though market validation remains limited
Smart Home and Access Control Market Reality
The 2025 Comparent survey reveals smart home and access control as an emerging technology category with limited adoption among vacation rental operators, suggesting early market development rather than mainstream acceptance.
Current Adoption Patterns
Only 99 out of 581 surveyed companies (17.0%) use smart home and access control solutions, making it one of the lower-adopted technology categories despite significant marketing attention in vacation rental media.
Smart home and access control leaders by actual usage:
- Point Central: 23 companies (23.2% of smart home users, 4.0% of all operators)
- RemoteLock: 21 companies (21.2% of smart home users, 3.6% of all operators)
- Lynx Automation: 18 companies (18.2% of smart home users, 3.1% of all operators)
- Operto: 13 companies (13.1% of smart home users, 2.2% of all operators)
- Kaba: 7 companies (7.1% of smart home users, 1.2% of all operators)
The relatively even distribution among top providers indicates no clear market leader has emerged, suggesting technology immaturity or diverse solution requirements preventing consolidation.
Traditional Access Management Reality
The 83.0% of operators not using smart access control rely on alternative approaches:
Manual key management: Physical key exchanges, lockboxes, or in-person check-ins that require coordination but avoid technology complexity and costs.
Basic code locks: Simple keypad locks with manually set codes that provide some automation without smart home integration or remote management capabilities.
Platform-dependent solutions: Reliance on Airbnb, Vrbo, and property management system basic access coordination without specialized smart home technology.
This high non-adoption rate suggests either cost-benefit concerns, operational complexity, or sufficient satisfaction with traditional access management methods.
Market Development Indicators
The 17.0% adoption rate and fragmented provider landscape indicate early-stage market development:
Technology experimentation: Early adopters testing various solutions without clear consensus on optimal approaches or providers.
Cost-benefit uncertainty: Limited proven ROI data making investment justification difficult for many operators.
Integration complexity: Smart home technology requiring technical expertise and ongoing maintenance that many operators prefer to avoid.
Traditional methods sufficiency: Current access management approaches meeting operational needs without requiring technology upgrades.
Leading Access Control Platforms
Based on the limited adoption data from the Comparent survey, these platforms represent the most widely used smart home and access control solutions among vacation rental operators.
Point Central - Market Leader
Point Central leads smart home adoption with 23 companies using the platform, representing 23.2% of smart home users and 4.0% of all surveyed operators.
Market Position:
- Slight leadership in fragmented market
- Focus on comprehensive smart home solutions beyond access control
- Integrated approach to property automation and monitoring
Point Central's leading position suggests it provides broader smart home capabilities that justify investment beyond simple access control, potentially including climate control, monitoring, and guest experience features.
RemoteLock - Close Secondary
RemoteLock holds 21 companies (21.2% of smart home users), establishing a competitive secondary position with adoption nearly matching the market leader.
Market Position:
- Strong competitive position with specialized access control focus
- Emphasis on vacation rental specific features and integrations
- Dedicated smart lock management and guest access automation
RemoteLock's competitive position indicates successful specialization in access control rather than broader smart home solutions.
Lynx Automation - Third Position
Lynx Automation captures 18 companies (18.2% of smart home users), representing the third-largest adoption among smart home solutions.
Market Position:
- Notable market presence with automation focus
- Integration capabilities with vacation rental operational systems
- Specialized approach to property automation and guest management
Lynx Automation's position suggests successful integration with vacation rental workflows and operational requirements.
Operto - Multi-Category Presence
Operto appears across multiple survey categories, indicating an integrated platform approach:
Cross-category adoption:
- Smart home and access control: 13 companies (13.1% of smart home users)
- Operations management: 14 companies (9.1% of operations users)
- Guest screening: 8 companies (47.1% of screening users)
- Digital guidebooks: 14 companies (20.6% of guidebook users)
This multi-category presence suggests Operto provides comprehensive vacation rental management solutions rather than specialized smart home focus.
Market Fragmentation Analysis
The smart home and access control category shows significant fragmentation with no dominant provider:
Top providers serve only 76.8% of adopters combined, indicating substantial market distribution among smaller providers and suggesting diverse solution requirements or early market development.
This fragmentation pattern, combined with low overall adoption (17.0%), indicates the smart home market serves specialized needs rather than universal operational requirements.
Essential Smart Home Features and Integration
Given the low adoption rates, successful smart home and access control platforms must provide exceptional value to justify investment over traditional access management approaches.
Integration with Universal Technologies
Smart home platforms must coordinate with universally adopted vacation rental technologies to provide operational value:
Property Management System Integration (100% adoption): Access control systems need seamless integration with leading PMS platforms like Hostfully (25.6%), Guesty (19.8%), and Track (15.3%) to automate guest access based on booking data.
OTA Platform Coordination: With Airbnb (94.8%), Vrbo (88.6%), and Booking.com (65.2%) adoption, smart home systems must sync access permissions with booking schedules across all major platforms.
Revenue Management Coordination (91.9% adoption): Access control timing should align with dynamic pricing strategies and optimal guest experience delivery without disrupting revenue optimization.
Core Access Control Features
Automated code generation based on booking confirmations eliminates manual access management while ensuring security through unique codes for each guest stay.
Remote monitoring and control enables property managers to handle access issues, grant emergency access, and monitor property security without physical presence.
Integration with cleaning and maintenance workflows coordinates access for service providers based on booking schedules and operational requirements.
Guest communication automation delivers access codes and instructions through integrated messaging systems that sync with booking platforms and PMS solutions.
Technology Sophistication Requirements
Smart home adoption correlates with overall technology sophistication, suggesting these platforms serve operators with comprehensive technology strategies rather than standalone access solutions.
Advanced operational coordination: Integration with operations management (26.5% adoption), guest communications (22.2% adoption), and market data platforms (32.9% adoption).
Scalability requirements: Smart home technology becomes more valuable for larger portfolios where manual access management becomes unsustainable.
Guest experience enhancement: Premium properties and sophisticated operations may justify smart home investment for competitive differentiation and enhanced guest experiences.
Strategic Implementation Considerations
The 17.0% adoption rate for smart home and access control indicates these solutions serve specific operational needs rather than universal requirements, making strategic evaluation crucial.
Investment Justification Framework
Portfolio size analysis: Smart home technology may become cost-effective beyond certain property counts where manual access coordination becomes time-intensive and error-prone.
Property type considerations: Premium properties, remote locations, or high-security requirements may justify smart home investment more readily than basic accommodations.
Operational complexity assessment: Multi-platform distribution (100% OTA adoption) combined with sophisticated pricing (91.9% revenue management adoption) may create coordination complexity that smart home automation addresses.
Guest experience differentiation: Markets with sophisticated competition may reward smart home amenities through higher rates or booking preferences.
Cost-Benefit Analysis
The 83.0% non-adoption rate suggests careful cost-benefit evaluation is essential:
Technology costs: Hardware, software subscriptions, installation, and ongoing maintenance expenses must be weighed against operational benefits and revenue improvements.
Operational savings: Time savings from automated access management, reduced coordination requirements, and improved guest experience efficiency.
Risk mitigation: Enhanced security, access tracking, and property monitoring benefits compared to traditional access management approaches.
Competitive positioning: Marketing advantages and guest satisfaction improvements that may justify investment beyond pure operational efficiency.
Integration Strategy
Smart home adoption works best as part of comprehensive technology strategies rather than isolated implementations:
Foundation technology optimization: Ensure PMS (100% adoption), revenue management (91.9% adoption), and OTA integration perform effectively before adding smart home complexity.
Complementary technology coordination: Smart home systems provide enhanced value when integrated with operations management (26.5% adoption) and guest communication systems (22.2% adoption).
Scalability planning: Smart home investment should align with business growth plans and operational scaling requirements rather than current-state optimization alone.
The survey data indicates that smart home and access control technology serves enabling functions for sophisticated vacation rental operations rather than universal operational requirements.
Future Market Development
The 17.0% adoption rate and fragmented provider landscape suggest smart home and access control technology remains in early development stages with significant growth potential as costs decrease and integration improves.
Growth Opportunity Analysis
Market expansion potential: 83.0% of operators currently use traditional access management, representing substantial automation opportunity as technology matures and costs decline.
Technology sophistication progression: The correlation between smart home adoption and overall technology sophistication suggests adoption will increase as industry technology capabilities develop.
Operational scaling drivers: Operators expanding beyond manual coordination capabilities may increasingly require smart home solutions for efficient multi-property management.
Technology Development Trends
Cost reduction: Hardware costs and installation complexity may decrease, lowering barriers to adoption for smaller operators currently using traditional access methods.
Integration improvement: Better integration with leading PMS platforms and operational systems may increase value propositions and reduce implementation complexity.
Feature enhancement: Advanced capabilities like AI-powered guest behavior analysis, predictive maintenance, and comprehensive property automation may justify investment beyond basic access control.
Market Consolidation Potential
The current fragmentation (top provider serves only 23.2% of adopters) suggests opportunities for consolidation:
Comprehensive solution providers: Platforms offering integrated access control, operations management, and guest experience features may capture larger market share.
PMS integration: Leading PMS providers may develop internal smart home capabilities rather than requiring separate smart home providers.
Technology ecosystem approach: Smart home solutions that integrate seamlessly with revenue management, operations, and communication systems may achieve competitive advantages.
The survey data suggests that smart home and access control will remain specialized solutions serving sophisticated operations rather than achieving universal adoption like PMS (100%) or revenue management (91.9%) technologies in the near term.
Frequently Asked Questions
Understanding vacation rental access control software requires recognizing the limited current adoption and evaluating whether smart home technology provides sufficient value over traditional access management approaches.
How widely adopted is smart home and access control technology among vacation rental operators?
Based on the 2025 Comparent Ultimate Tech Stack Survey of 624 vacation rental companies, only 99 operators (17.0%) use smart home and access control solutions.
This means 482 companies (83.0%) manage guest access through traditional methods like physical keys, basic code locks, or manual coordination without smart home technology.
Among the limited adopters, Point Central leads with 23 users (23.2% of smart home users), followed by RemoteLock with 21 users (21.2%) and Lynx Automation with 18 users (18.2%).
The low adoption rate indicates smart home technology serves early adopters and specialized use cases rather than mainstream vacation rental operations.
What are the leading smart home and access control platforms for vacation rentals?
The survey reveals a fragmented market with no clear dominant provider among the limited adopters:
Point Central leads slightly with 4.0% of all operators using their platform, followed closely by RemoteLock at 3.6% and Lynx Automation at 3.1%.
Operto appears across multiple technology categories including smart home (2.2% of all operators), suggesting an integrated platform approach rather than specialized access control.
The fragmentation suggests diverse solution requirements or early market development preventing consolidation around dominant solutions.
This pattern differs significantly from other technology categories that show clear market leaders, indicating smart home technology lacks consensus on optimal approaches.
Why do most vacation rental operators choose not to use smart home access control?
The 83.0% non-adoption rate suggests several potential barriers to smart home technology adoption:
Cost-benefit analysis may not justify smart home expenses relative to traditional access management approaches for many property types and operational scales.
Traditional methods like lockboxes, in-person check-ins, or basic keypad locks may provide sufficient security and convenience without technology complexity.
Integration requirements with existing PMS and operational systems may create implementation challenges that outweigh smart home benefits.
Technical maintenance and support requirements may exceed capabilities or preferences of operators focused on core hospitality rather than technology management.
The low adoption indicates that smart home solutions haven't yet achieved compelling value propositions for mainstream vacation rental operations.
What benefits do the 17% of operators using smart home technology report?
While the survey doesn't provide specific benefit data, the limited adopters likely value automated guest access management, remote property monitoring and control, and integration with booking systems for streamlined operations.
Smart home technology may provide competitive differentiation for premium properties or sophisticated operations seeking enhanced guest experiences.
Operational efficiency improvements through automated access code generation, remote troubleshooting, and reduced coordination requirements may justify investment for larger portfolios.
However, the low adoption rate suggests these benefits may not outweigh costs and complexity for most vacation rental operations.
How does smart home adoption correlate with other vacation rental technologies?
The survey shows smart home adoption correlating with overall technology sophistication, suggesting these solutions serve operators with comprehensive technology strategies.
Companies using smart home technology likely also adopt advanced solutions in operations management (26.5% overall adoption), guest communications (22.2% adoption), and market data platforms (32.9% adoption).
Integration with universally adopted technologies like PMS (100%), revenue management (91.9%), and OTA platforms becomes crucial for smart home value realization.
The correlation patterns indicate that smart home technology works best as part of integrated technology ecosystems rather than standalone access control solutions.